Why Bitcoin Is Stuck Near $65,000 as AI Fuels Inflation
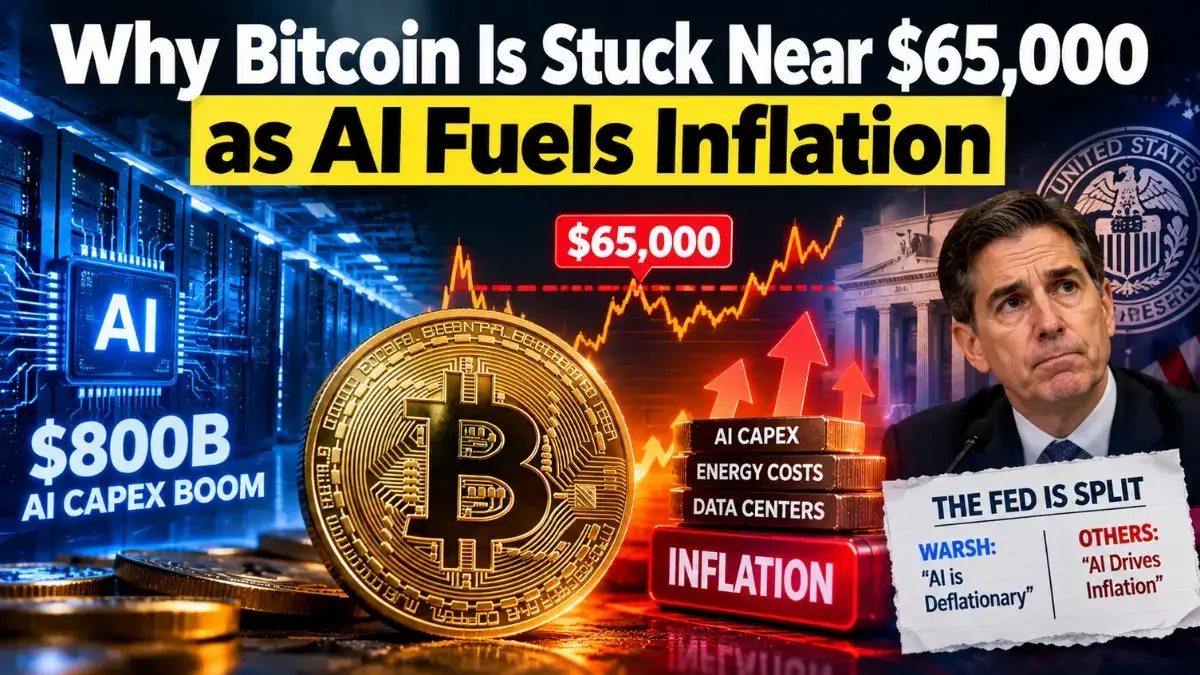
Through the summer of 2026, Bitcoin traded in a tight band around $62,000 to $67,000 while an $800 billion AI construction boom pushed up electricity, materials and specialist labour costs, killing the case for rate cuts. The consensus explanation was that AI-driven inflation had put a ceiling on Bitcoin. Then Bitcoin traded above $82,000 in early September, into a market pricing a rate hike. The ceiling thesis was mostly right about the mechanism and wrong about the conclusion, and the reason is worth understanding.
Key takeaways
- Goldman Sachs projects AI-related capital spending approaching $800 billion in 2026, rising toward $1.6 trillion by 2031. TrendForce puts the nine largest cloud providers alone near $830 billion, roughly 79% growth year over year.
- Fed Governor Lisa Cook flagged electricity and water prices each rising about 5% over a year. Jerome Powell said in March 2026 the construction activity was “probably pushing inflation up.”
- Fed Chair Kevin Warsh takes the opposite long-run view, arguing AI will prove structurally disinflationary.
- Bitcoin fell to around $63,600 by early June, briefly under $62,000, alongside an 11-session ETF outflow streak totalling roughly $3.45 billion, the longest since the funds launched in 2024.
- By early September Bitcoin traded above $82,000, then pulled back to around $79,600 on a hot payroll report.
The capex numbers are the whole story
Start with the scale, because the inflation argument only makes sense once you see it.
| Source | Figure | Detail |
| Goldman Sachs | ~$800B | AI-related capex, 2026 |
| Goldman Sachs | ~$1.6T | Projected annual AI capex by 2031 |
| TrendForce | ~$830B | Nine largest cloud providers, 2026, ~79% YoY growth |
| Goldman Sachs | +3.3pp | AI contribution to capex growth |
| Goldman Sachs | 7.8% | Full-year business investment growth forecast |
| Microsoft | ~$25B of $190B | Allocated to more expensive memory and components |
That Microsoft line is the one to sit with. A quarter of a hundred billion dollars, inside a single company’s budget, absorbed by component prices going up rather than by buying more things. That is not a forecast of inflation. That is a company reporting it.
How a data centre shows up in the CPI
The thing that makes AI capex inflationary is that almost none of it is software.
To stand up a large AI cluster you need land, then steel, then transformers, then copper, then generation capacity, then cooling infrastructure, then the specialised trades who know how to install all of it. Every one of those is a physical input with a supply curve that cannot respond in a quarter. You cannot manufacture a grid transformer faster because demand went up; the lead times were already measured in years before AI arrived.
Cook’s data point is the cleanest evidence. Electricity and water prices each up roughly 5% over a year. Electricity is not a niche input. It flows into the cost of nearly everything, with a lag, and it lands directly in household bills where people notice it.
Add the wage effect. Specialty construction trades have seen noticeable pay increases, because there is a finite number of people who can build a high-density power distribution system and suddenly everyone wants them at once. Wage increases in a constrained trade do not reverse when the building stops.
Powell’s March 2026 assessment was that this construction activity was “putting pressure on all kinds of goods and services” and was “probably pushing inflation up.” Governor Michael Barr went further and said the AI boom does not warrant lowering policy rates.
That is the transmission chain: AI capex to physical input demand to electricity and materials prices to headline inflation to a Fed that will not cut.
The Fed is split, and the split is about timing
Here is the part that most coverage of this story leaves out entirely, and it changes how you should read everything above.
Kevin Warsh, who became Fed Chair in May 2026, has argued that AI will prove structurally disinflationary.
That looks like a direct contradiction of Cook, Barr and Powell. It is not. It is a disagreement about horizon, and both sides are probably right about their own timeframe.
Building the infrastructure is inflationary. It consumes scarce physical inputs, bids up wages in constrained trades, and adds demand without adding near-term supply of anything consumers buy. That is the Cook and Barr view, and the data supports it right now.
Using the infrastructure is disinflationary. If AI systems reduce the labour input required per unit of output across a meaningful slice of the economy, that is a productivity shock, and productivity shocks push prices down. That is the Warsh view, and it is a claim about 2029 rather than about this quarter.
Railways were inflationary while they were being laid and disinflationary once they ran. Same for the electrical grid. The pattern is well documented in economic history and it has a name in the literature, but it also has an awkward property: the inflationary phase is measured in years and arrives first.
For a central banker, that creates a genuinely hard problem. Do you tighten into a supply-side investment boom that will eventually lower prices? Tighten too hard and you slow the build-out that produces the disinflation. Do nothing and you risk inflation expectations coming unanchored while you wait for a productivity payoff that might not arrive on schedule.
That tension, more than any single data release, is what is driving Fed policy in 2026. And it explains why the July FOMC was a 9-3 hold rather than a clean decision.
Also read: Bitcoin and Gold Fall As US Payrolls Crush Forecasts by 3x
Why this capped Bitcoin in August
The mechanism through to crypto is straightforward once the macro is clear.
Bitcoin’s price is highly sensitive to the expected path of real interest rates and dollar liquidity. It generates no yield. When risk-free assets pay more, the opportunity cost of holding a non-yielding asset rises, and marginal buyers step back.
Through June and into August that is exactly what showed up in the flow data. Bitcoin ETFs saw an 11-session outflow streak totalling roughly $3.45 billion, the longest redemption run since the products launched in 2024. Bitcoin slid to about $63,600 by early June and briefly traded under $62,000. The August 1 low was $62,101.
By August 10 the picture was a market with no direction: consolidating above $65,000, capped by resistance between $65,500 and $67,000, with holders who bought at those levels using rallies to reduce exposure. Options open interest sat around $26 billion with calls at roughly 60% of positions, which describes a market positioned for an upside break that kept not happening.
The explanation on offer at the time was tidy. AI capex means sticky inflation, sticky inflation means no rate cuts, no rate cuts means no liquidity impulse, and therefore Bitcoin stays capped.
Then it broke $80,000
By early September, Bitcoin traded above $82,000.
It did that while the macro backdrop got worse, not better. Warsh warned about inflation at Jackson Hole in late August. August payrolls came in at 162,000 against a consensus near 56,000. Odds of a September rate hike moved to around 65%. Two-year and five-year Treasury yields hit fresh 52-week highs.
Every input in the ceiling thesis moved against Bitcoin. Bitcoin went up roughly 30% from the August range anyway.
So the thesis needs revising, and the honest revision is this: the AI inflation story was never a ceiling. It was a description of one input into a market that has several.
What appears to have actually happened is that the summer range was a positioning phenomenon rather than a macro one. Holders trapped at $65,000 were supplying stock into every rally, which is a finite condition. Once that supply cleared, and once ETF flows turned from redemption to creation, the price moved to where the next real seller sat. That level turned out to be a long way up, because the summer grind had exhausted the sellers below it.
The macro did not permit the move. The macro was simply not the binding constraint.
This is a recurring error in crypto market commentary. Macro narratives are always available, always plausible, and always retrofittable. Positioning and flow are harder to see and explain far more of the short-run price action. When a clean macro story fails to predict a 30% move, the problem is usually that the story was describing the weather while the flows were moving the ship.
What the AI inflation story is still good for
None of the above means the AI capex analysis is worthless. It just operates on a different timescale than a monthly candle.
Over a multi-year horizon, the question of whether the AI build-out is net inflationary or net disinflationary determines the level of real rates, and real rates are the single largest structural input into Bitcoin’s valuation. If Warsh is right and the productivity payoff arrives, real rates fall, liquidity expands, and that is a durable tailwind. If Cook and Barr are right and the inflation proves persistent, real rates stay elevated for years, and Bitcoin faces a permanent headwind that no amount of ETF flow will offset.
That is a genuine fork, it will take years to resolve, and it matters far more than any individual monthly print.
What to watch
- Electricity CPI, not headline CPI. It is the cleanest read on whether the AI build-out is still pushing prices, and it is published monthly.
- Capex guidance from the hyperscalers. If 2027 guidance comes in below the roughly $830 billion 2026 run rate, the inflationary phase is peaking and the disinflation debate starts for real.
- Net ETF creations, weekly. More predictive of the next few weeks of Bitcoin price than any macro variable.
- Fed dissents. The 9-3 July vote showed the committee is genuinely divided. Watch whether the dissent count grows or shrinks, because that tells you which side of the inflation timing argument is winning inside the building.